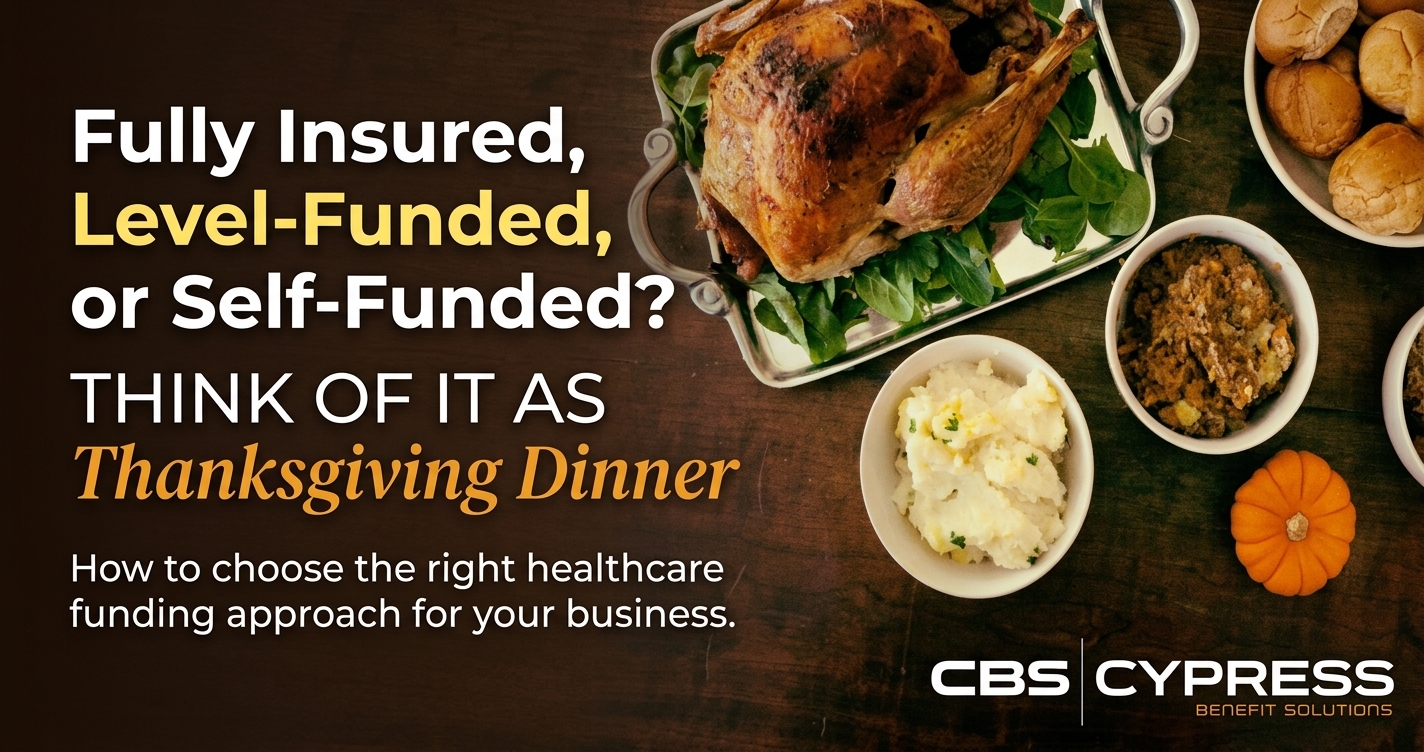
Every employer with a health plan faces the same question that every Thanksgiving host faces. How do we feed everyone, what will it cost, and what happens when more people show up than expected? The way a health plan is funded decides who carries that risk and who keeps the savings.
With Thanksgiving next week, the dinner table is a useful way to explain it. This post uses a holiday meal to describe funding approaches in plain language, followed by the questions worth asking before you decide. Like any analogy, it simplifies. Real health plans involve contracts, claim timing, and regulation that a turkey does not. The goal is a clear mental model and not a technical manual.
The Catered Dinner: Fully Insured
You hire a caterer and pay a fixed price per plate. The caterer buys the food, does the cooking, and takes the risk. If more guests show up or everyone eats more than expected, the price you agreed to does not change during the year. If fewer people eat, nothing comes back to you. Next year’s price is reset at renewal.
- Advantage: A known cost, little administrative effort, and the carrier carries the claims risk.
- Tradeoff: The price includes a cushion for the carrier’s risk and margin, there is no refund when the year goes well, and the claims detail you receive is often limited.
- Tends to fit: Employers who want predictability and a hands-off arrangement.
Catering With a Refund Policy: Level-Funded
You still pay the same amount every month, as with the catered dinner. That payment is built from 3 parts: money set aside to pay expected claims, the cost of a stop-loss policy (the backup plan described below), and administration. If the guests eat less than expected, the contract may return some or all of the unused claims money at the end of the year. If they eat more, the stop-loss policy covers claims above the limit, so the monthly payment stays level during the year. The cost of a bad year tends to show up at renewal.
- Advantage: A predictable monthly cost with a chance to share in good results.
- Tradeoff: The refund is not guaranteed, and the terms vary, since surplus is often shared between the employer and the carrier depending on the design. A bad year can raise the next renewal, and carriers underwrite the group, so groups with higher expected claims may not qualify or may see different terms.
- Tends to fit: Employers who want a step toward self-funding with a steady monthly bill.
Cooking It Yourself: Self-Funded
You buy the ingredients and pay for what is eaten, as it is eaten. You choose the menu, which is the plan design. You see everything that goes on the table, which is detailed claims data. When fewer people eat, you keep the savings. You also carry the risk that more guests arrive or that someone has a very large appetite, and the bills arrive unevenly. A plan can face $2,000 in claims in a quiet month and $15,000 in the next.
Most employers hire a third-party administrator, which acts like a kitchen manager that processes claims and manages the network. The employer remains responsible for overseeing that work.
- Advantage: Transparency, control over plan design, and the opportunity to keep savings.
- Tradeoff: Variable monthly cash flow, real risk even with protection in place, and more involvement from leadership.
- Tends to fit: Employers with the financial capacity to absorb a difficult year and leaders who will engage with the data.
The Backup Pizza Fund: Stop-Loss
Level-funded and self-funded plans usually rely on stop-loss insurance, which is the backup plan for when the dinner goes off script. It comes in 2 main forms, with 2 complications worth knowing.
- Specific stop-loss covers a single very large claim. It is the guest with an enormous appetite. The employer chooses a per-person limit and pays up to that amount, and the stop-loss carrier reimburses eligible claims above it.
- Aggregate stop-loss covers total claims. It is the whole extended family showing up. It limits what the employer pays for the entire group in a year.
- Lasers: A laser assigns a higher limit to a specific individual with known high claims. It is the pizza place saying it will not cover a particular guest, and it can increase the employer’s real exposure beyond the headline terms.
- Claim timing: Claims are often paid months after the service happens, like a restaurant bill that arrives after the party. Some stop-loss policies offer run-out or run-in coverage to address this lag, and the length of that coverage varies by policy.
The Potluck: Group Captive
In a potluck, each family brings a dish, and the table is fuller than any single family could provide alone. A group captive works on a similar idea for mid-sized claims. A group of employers pools part of its risk. A potluck also comes with expectations. Each member is expected to contribute, to stay for the whole meal, and to be a reliable guest. A captive is not a cure for a high renewal, and it is not right for every employer. We covered how captives work in an earlier post, which is worth a read before considering a captive.
Where the Analogy Breaks Down
- A health plan covers a full year of care and not a single meal. Claims for services in 1 plan year can be paid in the next.
- Employees are not guests. Their health needs vary, and they rely on the plan for care.
- Real plans involve regulation, contracts, and underwriting that the analogy leaves out. No funding arrangement is better in every case. The right fit depends on your group’s claims, cash flow, and comfort with risk.
Questions to Ask Before Choosing a Menu
These are the questions worth putting to your advisor before you choose a funding arrangement.
- Which funding options were considered for my group, and why were some ruled out?
- What is the most my group could pay in a bad year, and how is that limit set?
- What claims data will I receive, and how often?
- When claims come in lower than expected, who keeps the savings, and under what terms?
- What happens at renewal after a good year and after a bad year?
- Are there lasers or other individual limits, and how is claim run-out handled?
At Cypress Benefit Solutions, we believe the best funding arrangement is the one that matches your group’s claims, cash flow, and comfort with risk, and not the arrangement that is talked about the most. If you would like to understand which option fits your group, we would welcome the conversation. From all of us at CBS, Happy Thanksgiving.